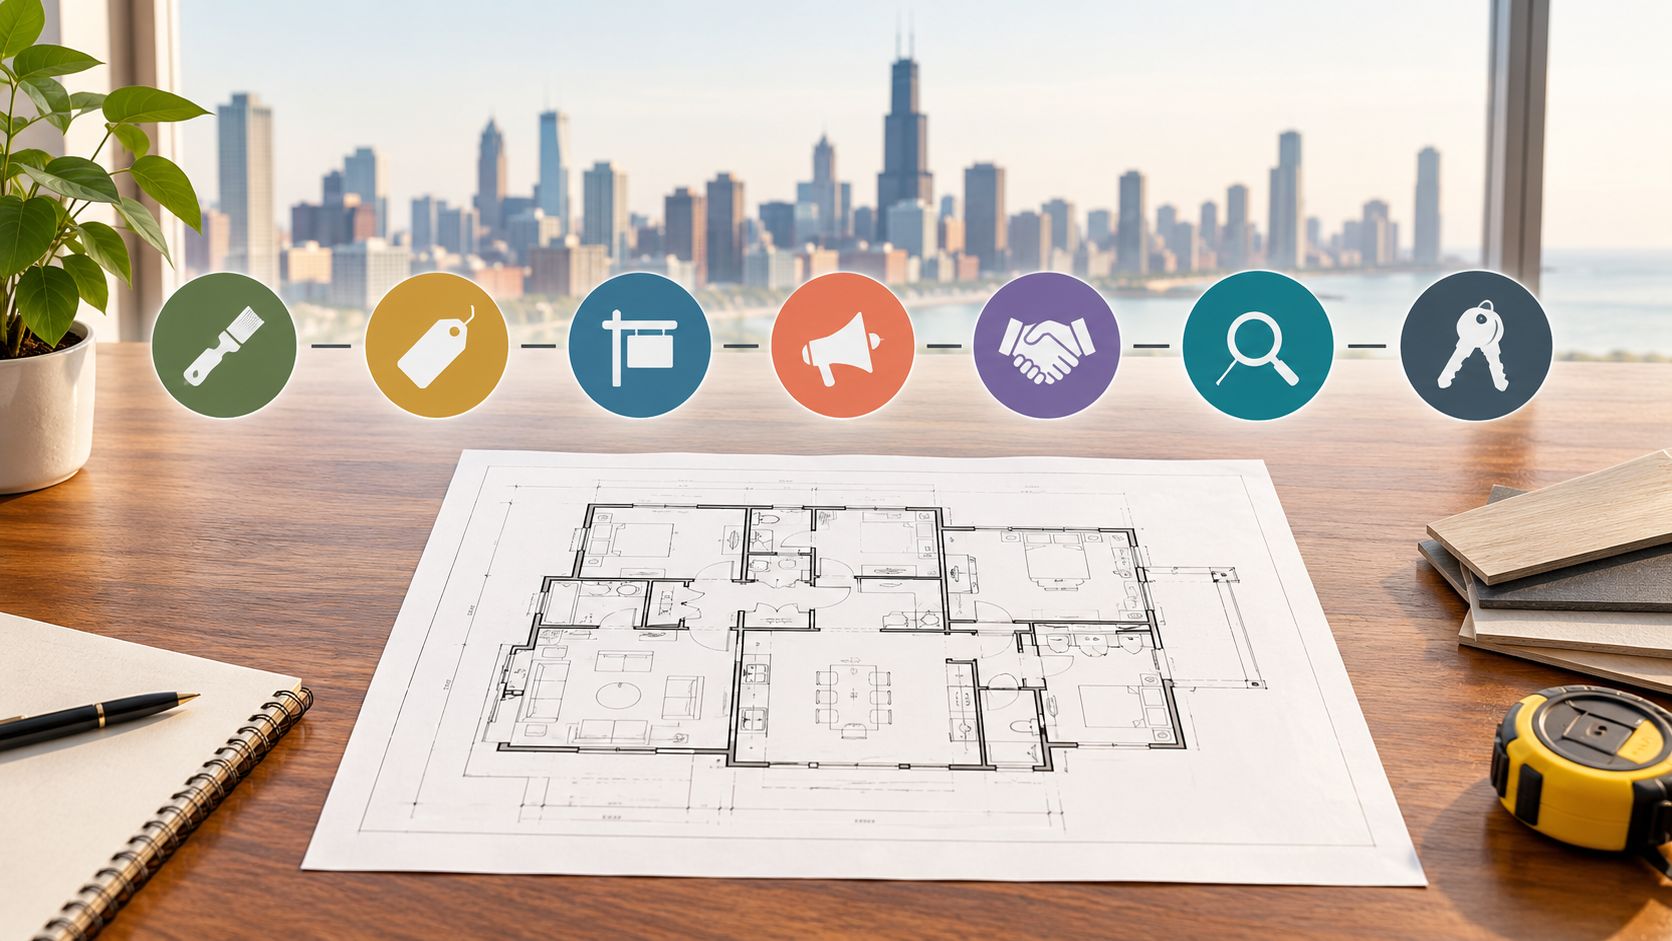
Your home may hold years of family memories, but buyers will evaluate it through condition, price, timing, and risk. In Melrose Park, Elmhurst, Oak Park, Downers Grove, Naperville, and Glen Ellyn, a successful sale depends on decisions made well before the first showing. The 7 steps of the selling process provide a useful framework, but residential transactions aren't perfectly linear. Pricing may need to change after buyer feedback, inspections can reopen negotiations, and lender or title requirements can affect the closing schedule. This roadmap connects preparation, MRED-supported pricing, coordinated marketing, offer strategy, contingencies, documentation, and ownership transfer. Timing varies with the property's condition, buyer financing, inspections, appraisal requirements, and title work, so the practical objective isn't to promise a fixed schedule. It's to keep every decision clear and every responsible party informed.
Table of Contents
- 1. Prepare Your Home and Gather Documentation
- 2. Price the Property Competitively Using Market Data
- 3. List the Property and Execute a Marketing Strategy
- 4. Review and Negotiate Offers
- 5. Conduct Inspections and Manage Contingencies
- 6. Finalize Closing Documents and Coordinate With Title and Lender
- 7. Close the Transaction and Transition Ownership
- 7-Step Home-Selling Process Comparison
- Turn the Seven Stages Into a Clear Selling Plan
1. Prepare Your Home and Gather Documentation
Preparation starts with making the property easier for buyers to understand and easier for professionals to sell. Decluttering, completing minor repairs, improving curb appeal, and organizing rooms can help photographs, showings, and inspections present a consistent story. A kitchen with fresh paint and orderly cabinets, for example, gives buyers fewer distractions and makes the space easier to evaluate.
Create a property file before the listing goes live. Include warranties, receipts, permits, renovation records, utility information, tax documents, and disclosure materials. A Melrose Park seller who located documentation for a recent roof replacement was better positioned to answer buyer questions and support the asking price. In Elmhurst transactions, gathering utility bills and tax records early has helped prevent document-related delays later.
Practical rule: Prioritize health and safety issues first, then focus on improvements buyers notice immediately, such as the entry, kitchen, bathrooms, lighting, and exterior presentation.
A professional stager or photographer can help show the home's potential, but preparation doesn't mean renovating everything. Expensive upgrades may not be recovered, while cleaning, paint touch-ups, organized storage, and visible maintenance can remove objections without over-improving the property.
For exterior priorities, use this curb appeal guide to focus your effort where buyers form their first impression. Review Illinois disclosure requirements early, and ask your real estate professional which records should be assembled before listing.
2. Price the Property Competitively Using Market Data
Pricing is often the most difficult stage because sellers remember what they invested, how much they love the home, and what they hope to net. Buyers, however, compare condition, location, size, updates, and competing inventory. A defensible price starts with evidence, not attachment.
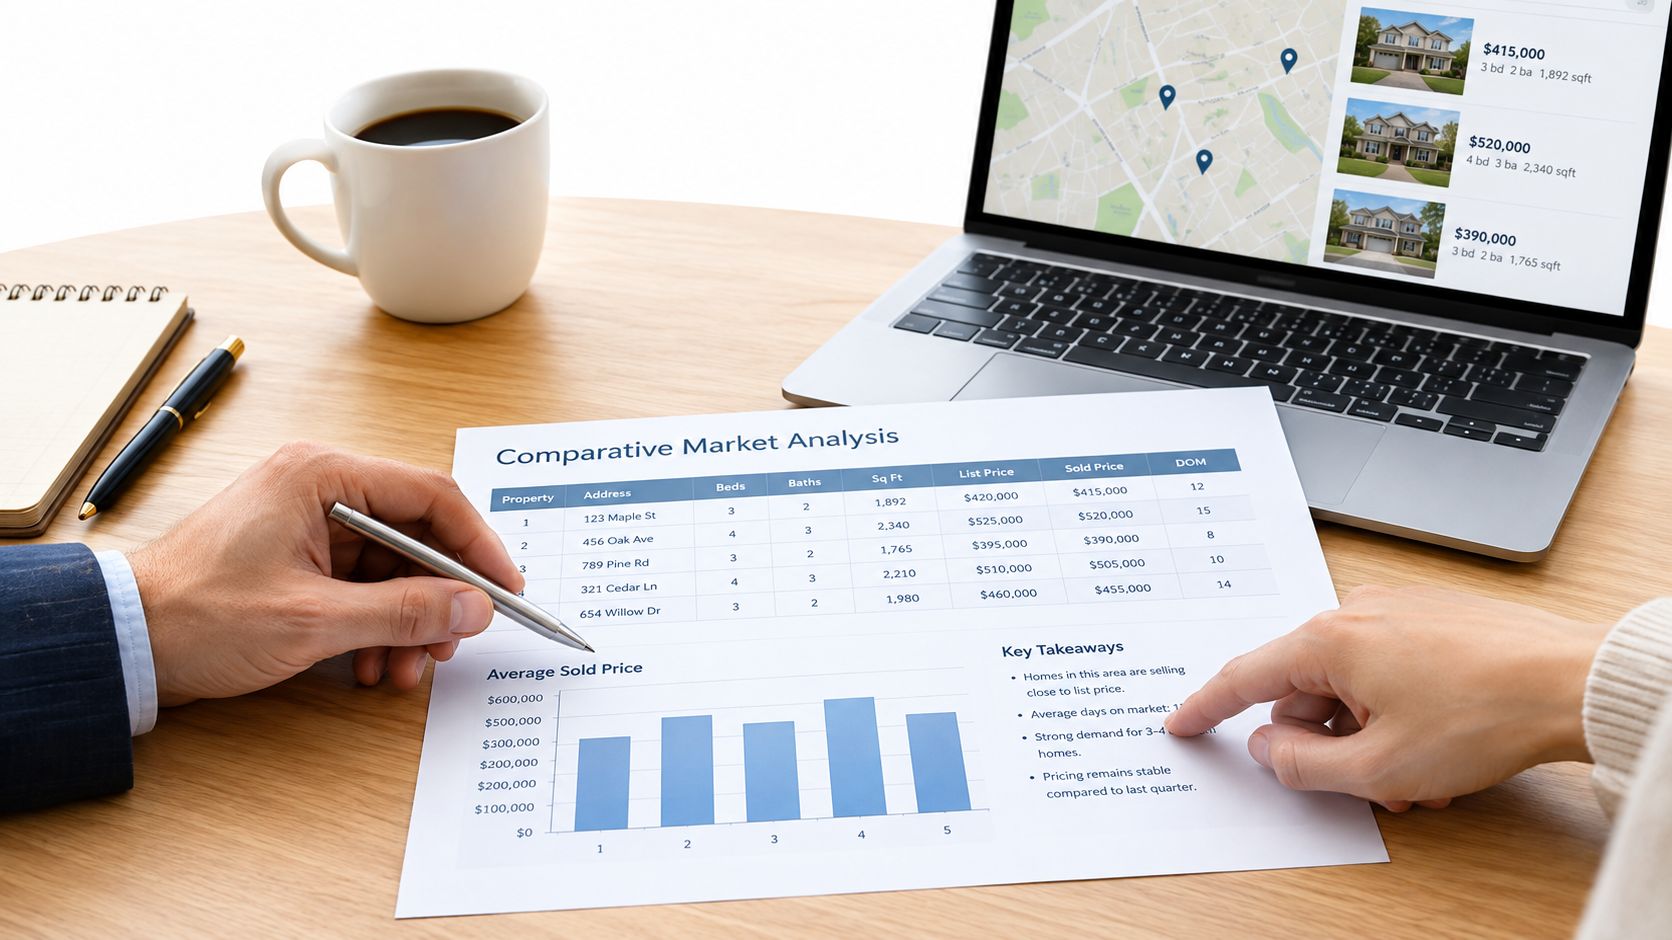
A comparative market analysis typically reviews recently sold, pending, and active properties. The strongest comparisons are similar in size, features, condition, lot, and location. One pricing guideline recommends reviewing properties sold within the prior six months and ideally within one mile, while another advises keeping the search criteria consistent across sold, active, and pending listings. Homes.com's pricing guidance explains why like-kind comparisons matter.
Carmen Salerno uses Compass MLS search and market analysis tools to review local evidence with sellers. In an Elmhurst example, a seller wanted $520,000, but a review of comparable sales, property condition, and buyer expectations supported a more realistic strategy. The conversation became easier once the numbers were separated from the home's emotional meaning.
Use the first weeks as a feedback window
Pricing isn't a one-time declaration. If the listing receives attention but no workable offers, showing feedback, competing properties, and buyer objections can reveal whether condition, presentation, or price is creating friction. NAR's 2024 consumer profile reported a median sale price of 100% of final list price for recently sold homes, while homes that stayed on the market 5 to 8 weeks sold at 98% of list price. The same profile reported that 65% of sellers never reduced price, while 21% reduced it once, supporting the importance of early validation. See NAR's pricing analysis for the reported figures.
For a property-specific plan, review this comparative market analysis resource and request a valuation before choosing a list date.
3. List the Property and Execute a Marketing Strategy
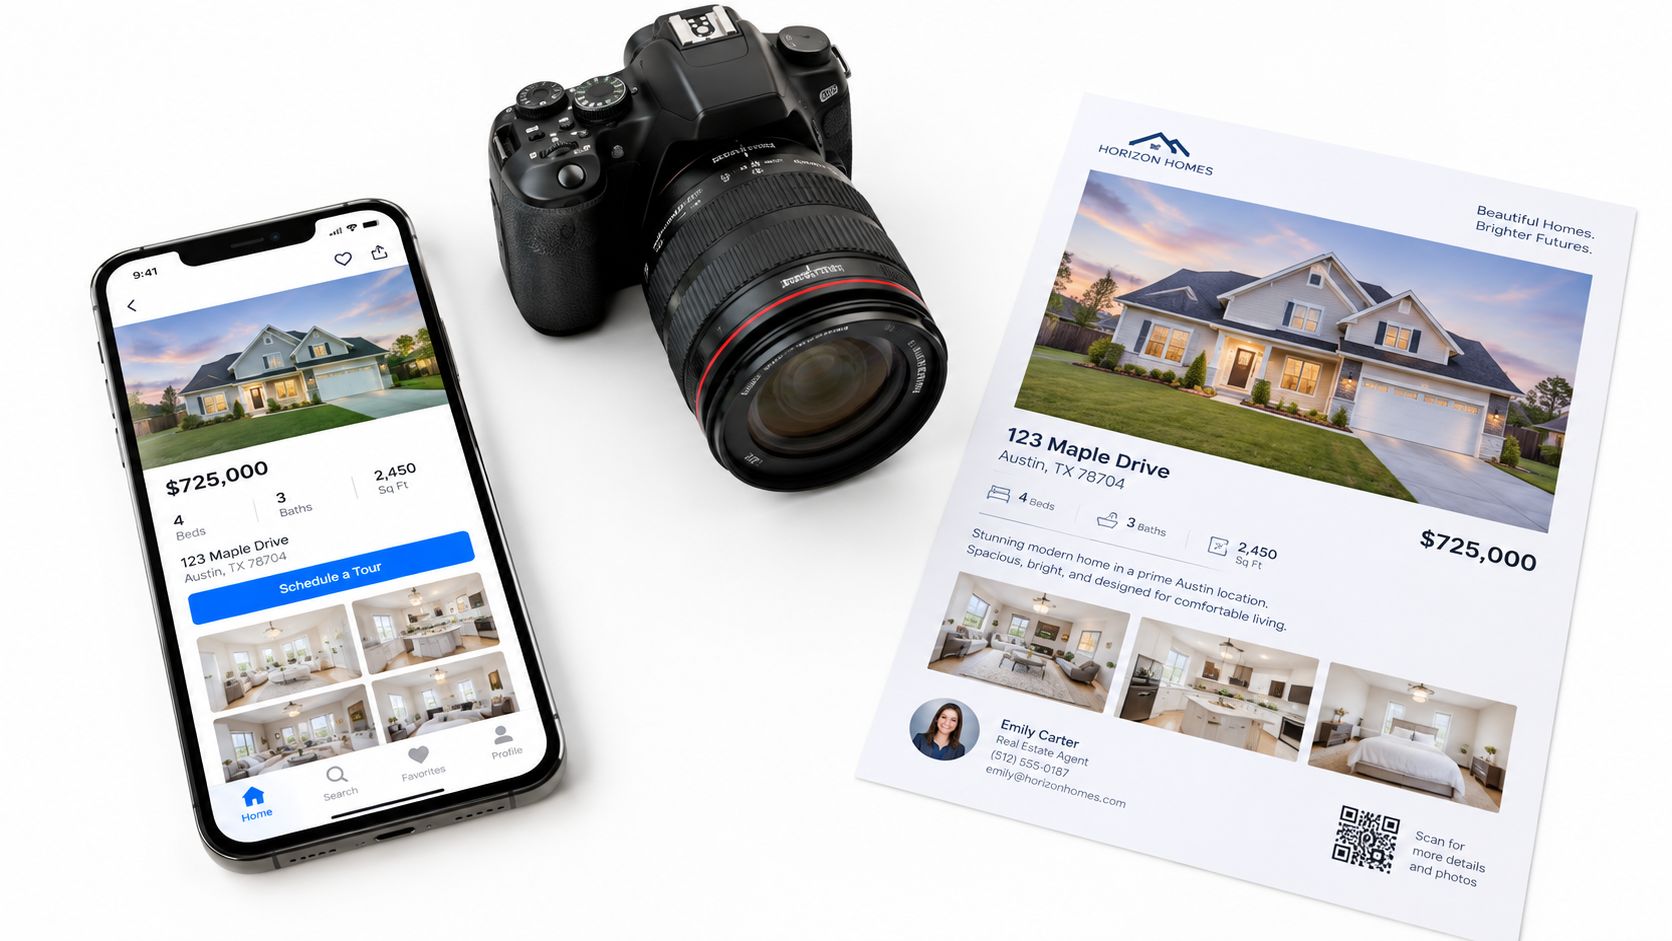
A listing succeeds when the right buyers can find it, understand it, and schedule a showing without unnecessary friction. MRED Broker Reciprocity provides the distribution foundation, while professional photography, accurate property details, social media, and convenient access support the buyer's next decision.
Homes By Carmen's recent listings have gone under contract quickly, but Carmen hasn't tracked which individual marketing tactic generated the most qualified showings or the exact margin compared with usual results. That distinction matters. Professional photography, strategic pricing, MLS exposure, and social media work together, and claiming one tactic caused an outcome without attribution data would be unreliable.
The listing description should connect features to practical buyer concerns. Mention updates, storage, parking, outdoor space, commute context, and neighborhood benefits accurately. A renovated kitchen deserves clear photography and precise description, not exaggerated language. Oak Park, Glen Ellyn, and other western suburbs can attract different buyer priorities, so the marketing should reflect the property's actual audience.
Make the showing process easy
Use a simple operating standard:
- Present the home consistently: Keep lighting, temperature, cleanliness, and access ready for scheduled appointments.
- Show the strongest features clearly: Use professional photography, and consider video or aerial media when the property and budget justify it.
- Collect useful feedback: Ask showing agents whether buyers objected to price, condition, layout, location, or missing information.
- Update promptly: Correct availability, price, disclosures, or property details as soon as they change.
MLS distribution remains central for sellers. NAR's 2025 generational trends reporting said 88% of sellers had their agent list on the MLS, while usage and certainty were lower among younger cohorts. The reported MLS findings reinforce the value of explaining exactly where and how a listing is being marketed.
4. Review and Negotiate Offers
An offer should be judged by its complete structure, not its headline price. Compare financing strength, earnest money, inspection and appraisal contingencies, requested credits, possession terms, and closing timing. A higher offer can create more risk when financing is uncertain or the deadlines conflict with the seller's plans.
Start by defining the seller's priority. That may be maximum proceeds, a specific moving date, an as-is sale, fewer contingencies, or greater confidence that the transaction will close. The response should support that priority. A counteroffer is more effective when it addresses the term that matters most instead of treating every difference as a dispute.
Consider a negotiation in which the seller wanted $520,000 and the buyer opened at $500,000. Carmen kept the discussion focused on the numbers and the seller's preferred terms. The parties agreed to $508,000, with the property sold as is. The final price added $8,000 to the initial offer, while the as-is provision protected the seller's desired condition of sale.
Compare terms before responding
An offer generally gives the seller three choices: accept, counter, or reject. A counteroffer can revise price, timing, contingencies, or other terms, so the decision should follow a careful review of the written proposal. That offer guidance supports responding to the offer's actual risks and benefits rather than reacting emotionally.
Use this review:
- Financial credibility: Check preapproval or proof of funds and understand the buyer's financing structure.
- Contingency exposure: Identify inspection, appraisal, sale-of-home, and other conditions that could delay or prevent closing.
- Timing fit: Compare closing and possession dates with the seller's relocation or purchase plans in Melrose Park or elsewhere in western Chicagoland.
- Concession alternatives: Consider a credit or repair arrangement when it addresses a buyer concern without lowering the headline price.
Document every amendment and agreement. Prompt, precise communication helps both sides understand what changed and keeps the transaction on schedule. A strong offer is the one that fits the seller's financial goals, timing, and tolerance for uncertainty.
5. Conduct Inspections and Manage Contingencies
After acceptance, the buyer usually schedules a professional inspection. The seller should review the report carefully, distinguish safety or structural concerns from routine maintenance, obtain dependable estimates, and respond within the contract's timeline. Each request deserves a practical answer, not an automatic concession.
Provide access to attics, crawl spaces, mechanical systems, and exterior components. If the inspector identifies a substantial defect, a contractor's estimate gives both parties a clearer basis for discussion. Depending on the agreement and the buyer's expectations, the seller may complete the work, offer a credit, adjust the price, or keep the property in its agreed as-is condition.
A roof problem illustrates the trade-off. Replacing the roof may create cost, scheduling, and disruption concerns, while a credit can address the buyer's risk without delaying the transaction. In one example, the seller negotiated a $12,000 repair credit. In another, an outdated HVAC system resulted in a $5,000 credit that satisfied the buyer and cleared the inspection contingency.
Keep the inspection conversation focused on resolution. The right response is the option that addresses the buyer's legitimate concern while protecting the transaction, not automatically the most expensive repair.
Track every deadline
Inspection, appraisal, financing, and attorney review periods may overlap. Confirm report delivery dates, response deadlines, and the date each contingency must be removed in writing. Ask the buyer to schedule promptly, and explain early when access or repair estimates will require additional time.
A separate ownership-record issue can also surface during this stage. In one Melrose Park transaction, an old contractor lien required coordination with the seller's attorney before it could be cleared. Organized records and early communication give the parties more time to address that problem than a last-minute discovery would.
After the inspection contingency clears, confirm that the appraisal has been ordered and continue monitoring lender requirements. Prompt, calm communication shows cooperation while preserving the seller's ability to evaluate requests based on documented facts.
6. Finalize Closing Documents and Coordinate With Title and Lender
Once contingencies are cleared, attention shifts to documents, title, and the funds required for closing. The deed, settlement statement, disclosures, title materials, prorations, lender conditions, and closing instructions must agree. The seller's attorney, title company, lender, buyer's representatives, and real estate professional each manage separate tasks, so assign responsibility and confirm updates in writing.
Start with the settlement figures. Check the purchase price, credits, commissions, taxes, insurance, association charges, payoff amounts, and other prorations. Confirm that the deed description matches the legal property information. Ask the appropriate professional to explain any unfamiliar fee or correction before signing.
Title problems can change the schedule. In one transaction, a mechanic's lien from a driveway contractor had to be released before closing. Carmen coordinated with the contractor, and the closing proceeded three days later. A short delay is preferable to transferring ownership with incomplete records or an unresolved lien.
Protect the final walkthrough
The final walkthrough is the buyer's last opportunity to confirm that the property remains in the agreed condition. Schedule it 24 to 48 hours before closing when possible. Complete promised repairs, remove remaining personal items, and document the home's condition. Agreed appliances, fixtures, keys, remotes, and manuals should remain in place.
Use a focused preparation check rather than relying on memory:
- Settlement documents: Verify the transaction terms, net proceeds, credits, prorations, and deductions.
- Title details: Confirm the deed description, payoff information, and lien status with the responsible professionals.
- Transfer procedures: Call the title company through a trusted number before authorizing any wire.
- Property condition: Address a damaged fixture, missing item, or incomplete repair before signing.
Closing schedules vary by lender, title work, and the issues uncovered during the transaction. Sellers can review this guide to closing on a house and plan around documented milestones rather than an assumed date. Clear updates between the seller, attorney, title company, lender, and buyer's representatives keep small discrepancies from becoming closing-day problems.
7. Close the Transaction and Transition Ownership
Closing brings the sale to its legal and financial finish. The seller signs the final documents, the buyer's lender funds the loan when applicable, and the title company completes the recording and transfer process. Possession and proceeds follow the written agreement and title procedures. Arrive prepared, review every figure, and ask questions before signing.
A closing date can change without putting the sale at risk. In one Melrose Park transaction, lender delays required two rescheduled closings. Carmen kept the seller informed, and the transaction closed three days late. Clear updates gave the seller a realistic timeline and prevented uncertainty from slowing decisions.
Review the final numbers as carefully as the offer. At another closing, a utility adjustment discrepancy appeared in the prorations. The title company found an error in the seller's favor and corrected the settlement. Closing funds were wired within 24 hours, after the deductions and adjustments were documented.
Leave with a complete record
Bring government-issued photo identification and every document requested by the title company. Use the appointment to confirm four practical details:
- Settlement statement: Check net proceeds, credits, prorations, and deductions against the agreed terms.
- Deed information: Confirm the property address and legal description.
- Transfer instructions: Verify the destination account and the title company's procedure for confirming wire details.
- Post-closing plan: Arrange utility shut-offs, mail forwarding, storage, possession, and key delivery according to the agreement.
Ask for copies of the signed deed and settlement statement before leaving. Keep warranties, repair records, tax information, and sale documents together for future reference. In western Chicagoland, careful coordination among the seller, attorney, title company, lender, and buyer's representatives helps the transaction finish on the revised schedule when a delay occurs.
7-Step Home-Selling Process Comparison
| Step | Implementation complexity | Resource requirements | Expected outcomes | Ideal use cases | Key advantages |
|---|---|---|---|---|---|
| Prepare Your Home and Gather Documentation | Moderate, time for inspection and staging | Time, minor repair budget, document organization, staging | Fewer delays, stronger buyer confidence, quicker show-readiness | Sellers preparing to list, homes needing repairs or records | Prevents surprises, accelerates closing, improves presentation |
| Price the Property Competitively Using Market Data | Moderate, analysis and strategy decisions | MLS/Compass access, agent CMA expertise, recent sales data | Accurate listing price, more qualified showings, reduced days on market | Sellers uncertain about value or in shifting markets | Data-driven pricing, maximizes proceeds, defensible rationale |
| List the Property and Execute a Marketing Strategy | Moderate–High, multi-channel coordination | Professional photography, advertising budget, social media, MLS | Increased exposure, higher inquiry rates, potential multiple offers | Sellers seeking broad reach and rapid buyer interest | Professional visuals, targeted reach, multi-channel momentum |
| Review and Negotiate Offers | High, tactical negotiation and comparison | Agent negotiation skill, offer analysis, market data, paperwork | Improved sale terms, higher net price, clarified contingencies | When offers received or multiple-offer scenarios arise | Can increase final price, tighten terms, speed closing |
| Conduct Inspections and Manage Contingencies | High, coordination and repair decisions | Inspection fees, contractor estimates, contingency management | Identified defects addressed, contingency removals, preserved deal | Post-acceptance, older properties, or homes with known issues | Reduces deal risk, enables strategic concessions, keeps timeline |
| Finalize Closing Documents and Coordinate with Title and Lender | Moderate–High, legal and financial coordination | Title company, lender, attorney, document review, wire instructions | Clean title, accurate settlement statement, scheduled closing | Pre-closing after contingencies clear | Prevents last-minute delays, ensures accurate funds transfer |
| Close the Transaction and Transition Ownership | Low–Moderate, final signings and transfer | Photo ID, signed documents, wire transfers, keys | Ownership transferred, seller receives net proceeds, possession changes | Day-of-closing activities | Formalizes sale, completes funds transfer, documents possession change |
Turn the Seven Stages Into a Clear Selling Plan
The seven stages are simple to name, but each one requires decisions that affect the next. Prepare the home thoroughly and gather records before marketing begins. Price from comparable evidence, property condition, and buyer expectations rather than from an emotional target. Launch a coordinated listing through MRED Broker Reciprocity, professional photography, accurate descriptions, and practical showing access.
When offers arrive, compare price and terms together. A buyer's financing, contingencies, closing date, possession request, and willingness to accept the property's condition can matter as much as the headline number. Negotiation works best when the seller knows which priority matters most and keeps the conversation focused on a workable agreement.
Inspections and contingencies require a measured response. Obtain facts, estimate meaningful repairs, and consider credits or as-is terms when they protect the transaction. Don't let an inspection report turn into an argument about every minor observation. Address material concerns promptly, document agreements, and track each deadline.
The final stages reward organization. Verify title, lien, lender, deed, settlement, and proration details with the appropriate professionals. Complete the final walkthrough carefully, confirm wiring instructions independently, and keep copies of the signed documents. Ownership transfer is a legal and financial event, not merely the moment keys change hands.
For sellers in Melrose Park, Elmhurst, Oak Park, Downers Grove, Naperville, and Glen Ellyn, the most useful next step is practical. Assemble renovation records, permits, warranties, tax information, utility details, and disclosure materials. Write down your preferred timing and identify whether your main priority is price, certainty, flexibility, or a particular possession date. Then request a complimentary valuation and strategy consultation from Homes By Carmen before committing to a listing date. A property-specific review can connect local market data with the home's condition and your personal objectives, giving you a clearer starting point for the 7 steps of the selling process.
Homes By Carmen offers seller representation with comparative market analysis, MRED listing exposure, showing coordination, offer negotiation, and transaction oversight for Melrose Park and western Chicagoland. Visit Homes By Carmen to request a complimentary valuation and strategy consultation before you list.